Asymptotic Confidence Ellipse for Lognormal Distribution with Applications in Actuarial Pricing

The problem
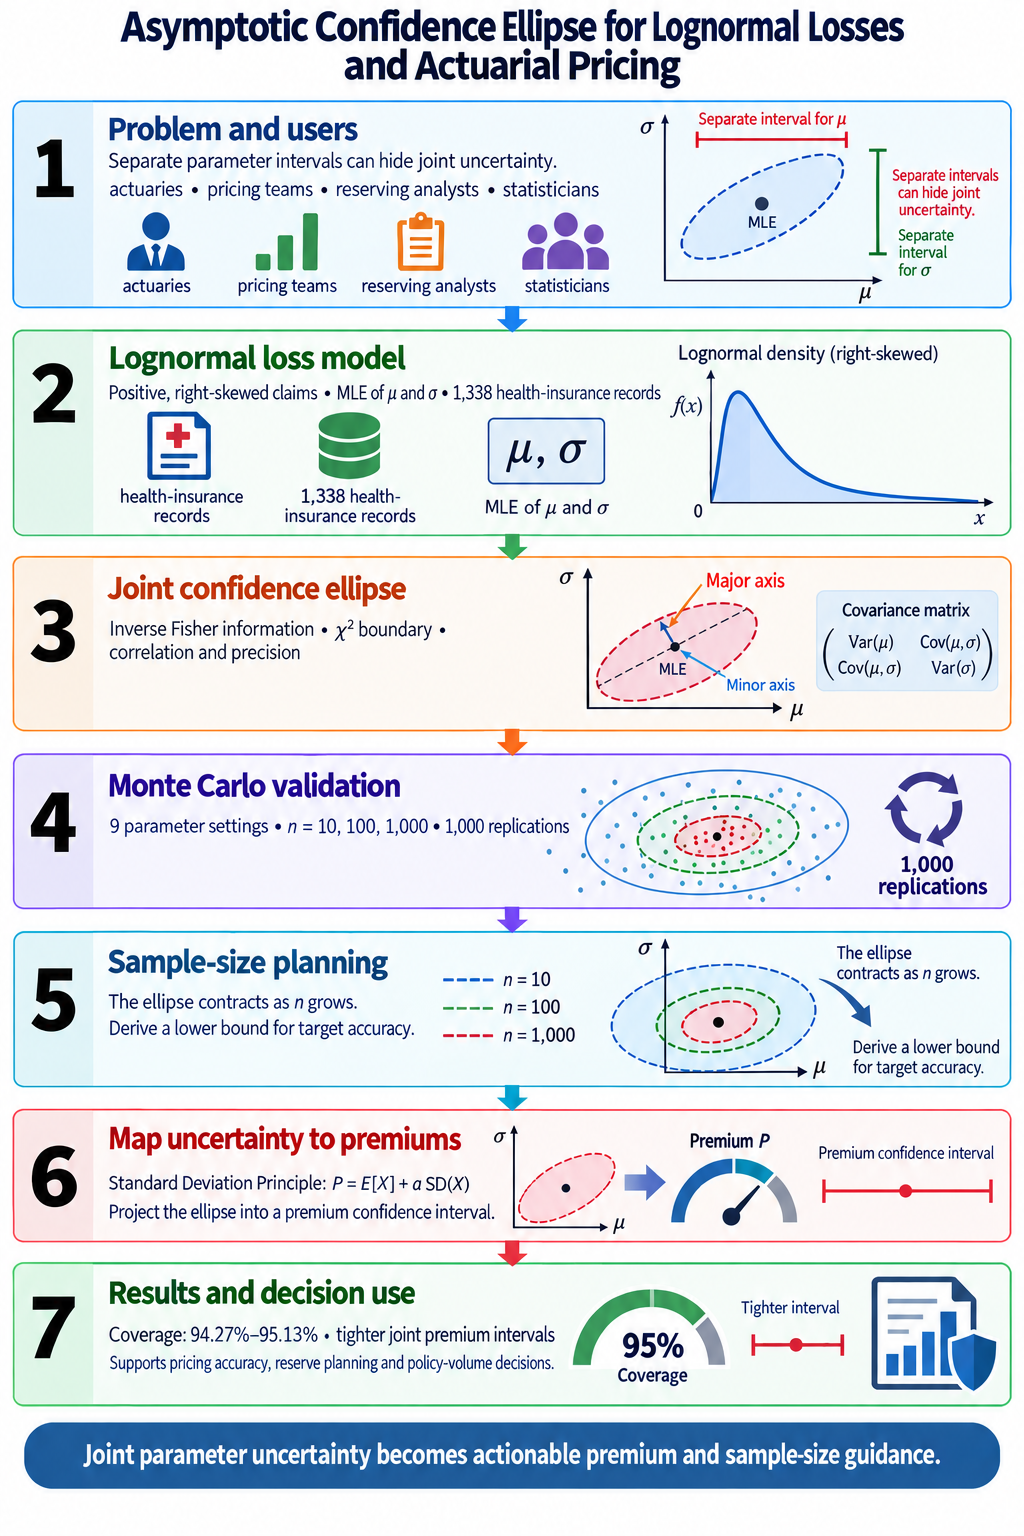
Actuarial pricing based on lognormal losses depends on two estimated parameters whose uncertainties are related. Separate intervals can hide this joint uncertainty and give insurers limited guidance about premium accuracy or the number of policies required.
Who benefits:
- Actuaries and insurance pricing teams
- Risk and reserving analysts
- Statisticians using lognormal models
- Insurers planning sample sizes and policy volumes
Method
The paper derives an asymptotic joint confidence ellipse from the maximum-likelihood estimators of lognormal parameters. Monte Carlo experiments use nine parameter settings, sample sizes of 10, 100, and 1,000, and 1,000 replications. A theoretical lower bound for the sample size needed to attain a chosen accuracy is derived, verified by simulation, and applied to 1,338 health-insurance records.
Results
Empirical coverage ranges from 94.27% to 95.13%, close to the nominal 95% level even for small samples. The joint ellipse produces tighter premium confidence intervals than treating parameters separately, while the derived sample-size relationship supports pricing accuracy, reserve planning, and policy-volume decisions.