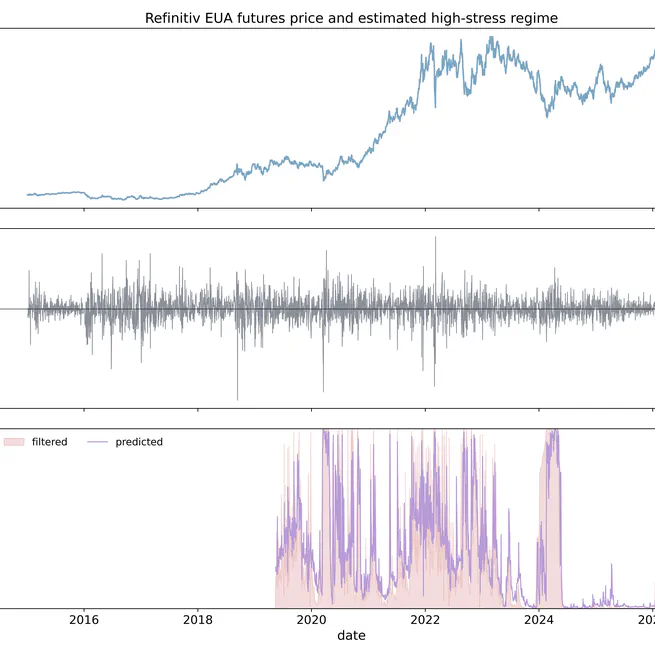
Policy-state gated regime dynamics in European emission allowance futures
A policy-state-gated regime model for interpreting low- and high-volatility conditions in European emission allowance futures.
Sep 13, 2026
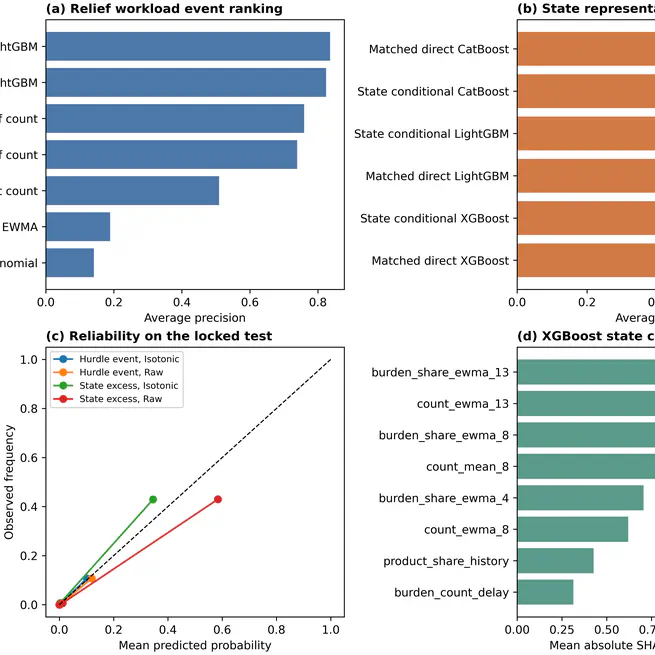
State Conditional Boosting for Prospective Early Warning of CFPB Reported Relief Workload
An explainable, prospective early-warning framework for prioritizing review of company-product cells with escalating CFPB-reported relief workload.
Sep 12, 2026

Stress-Responsive Lambda Value at Risk with a VIX-Driven Smooth Sigmoid Distortion
A VIX-driven Lambda Value at Risk framework that adapts tail-risk limits smoothly as market stress changes.
Jan 2, 2026

Asymptotic Confidence Ellipse for Lognormal Distribution with Applications in Actuarial Pricing
A joint confidence ellipse for lognormal parameters that supports premium uncertainty analysis and insurance sample-size planning.
Dec 24, 2025

A Stochastic Evolutionary Game Reformulation of the Lux--Marchesi Financial Market Model
A finite-population stochastic evolutionary extension of the Lux--Marchesi mechanism for analysing trader selection, fixation, regime persistence, and endogenous price feedback.
Dec 16, 2025

Structural Change Detection in Panel-MIDAS-ARDL Time Series Regression Models: An Application to Firm Values and ESG Scores
A three-stage Panel-MIDAS-ARDL and SBS-Cross-Entropy method for detecting sector-specific structural changes in the effect of ESG on ETF valuations.
Aug 8, 2025

Mechanisms for Implementing Fossil Fuel Divestment in Portfolio Management with Impact on Risk, Return and Carbon Reduction
A dynamic assessment of how fossil-fuel divestment schedules affect portfolio risk, return, stability, and carbon reduction.
Jul 3, 2024

DivFolio: a Shiny Application for Portfolio Divestment in Green Finance Wealth Management
An accessible R Shiny workflow for evaluating how ESG and carbon-divestment choices affect portfolio risk, return, diversification, and climate objectives over time.
May 13, 2024

Forward Jump Random Walk on a Cycle Graph and Its Hitting Time
Exact combinatorial formulas for arrival probabilities and hitting-time moments of a forward-jump random walk on a cycle graph.
Mar 29, 2024

Leveraging Generative Pre-trained Transformers for the Integration of Environmental, Social, and Governance Considerations into Investment Management for Thai Stock
A practical framework for using GPT models to integrate unstructured ESG information into Thai-stock analysis and investment management.
Mar 1, 2024