เทรดแบบ Quant — The Trading Lab EP.14
A full-length discussion of statistical arbitrage and the quantitative trading process, including hedging ratios, asset selection, correlation and cointegration, value at risk, mean reversion, cash-and-carry arbitrage, position sizing, and applications of machine learning and AI.
Aug 19, 2026
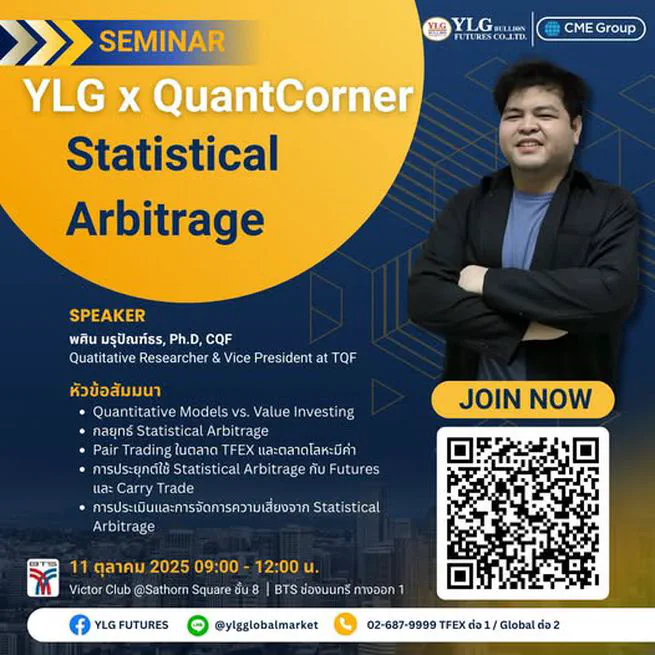
Statistical Arbitrage
A seminar on statistical-arbitrage strategies that combine quantitative models and value investing, including pair trading, carry trade, practical futures implementation, and risk management.
Oct 11, 2025