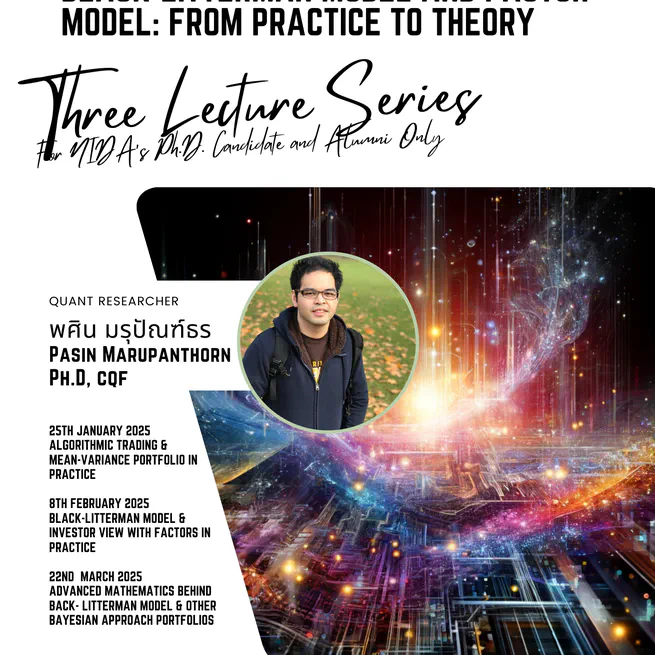
Introduction to Black-Litterman Model and Factor Model From Practice to theory
This lecture series provides a comprehensive journey from practical applications to theoretical foundations of the Black-Litterman Model and Factor Model in portfolio management. The sessions will explore algorithmic trading, Bayesian approaches, and the integration of investor views with factors in portfolio construction.
Jan 25, 2025

Mechanisms for Implementing Fossil Fuel Divestment in Portfolio Management with Impact on Risk, Return and Carbon Reduction
A dynamic assessment of how fossil-fuel divestment schedules affect portfolio risk, return, stability, and carbon reduction.
Jul 3, 2024

DivFolio: a Shiny Application for Portfolio Divestment in Green Finance Wealth Management
An accessible R Shiny workflow for evaluating how ESG and carbon-divestment choices affect portfolio risk, return, diversification, and climate objectives over time.
May 13, 2024

DivFolio
A Shiny Application for Portfolio Divestment in Green Finance Wealth Management
Oct 26, 2023
Goal-Based Portfolio Optimization
Goal-based portfolio optimization is a strategy that tailors investment decisions to meet specific financial objectives by aligning asset allocation and risk management with the investor's individual goals and time horizons.
Sep 12, 2023